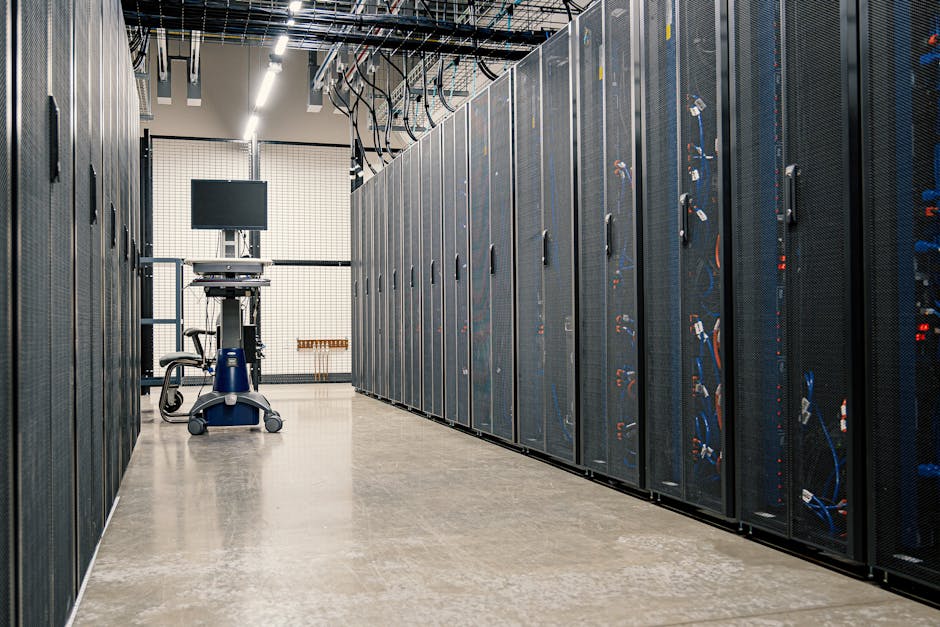
The migration from on-premise computing infrastructure to cloud-based infrastructure represents one of the most significant technology transitions facing mortgage lenders in the current era, as institutions of all sizes grapple with the limitations of legacy systems that were designed for a different era of lending volume, data complexity, and customer expectation. On-premise infrastructure, in which the lender owns and operates physical servers, storage, and networking equipment housed in its own data centers or colocation facilities, has been the traditional model for mortgage technology for decades, and it continues to serve as the computing backbone for a substantial portion of the mortgage industry. However, the limitations of on-premise infrastructure, including high capital costs, limited scalability, lengthy provisioning cycles, and the ongoing burden of hardware maintenance and software patching, have become increasingly apparent as lenders seek to modernize their technology platforms and respond to the competitive and regulatory pressures that define the contemporary mortgage market.
The cloud computing model, in which computing resources are delivered as a service over the internet from infrastructure operated by a cloud service provider, offers mortgage lenders a fundamentally different approach to sourcing and managing computing infrastructure. Cloud infrastructure eliminates the need for the lender to purchase, house, and maintain physical servers and networking equipment, replacing the capital expenditure model of on-premise infrastructure with an operational expenditure model in which the lender pays for computing resources on a consumption basis. The cloud model also provides scalability that is virtually impossible to achieve with on-premise infrastructure, as the cloud provider maintains a vast pool of computing resources that can be allocated to the lender on demand, enabling the lender to expand or contract its computing capacity in response to changes in origination volume, processing demand, or business strategy without the lead times and capital commitments that on-premise scaling requires.
The assessment phase of a cloud migration begins with a comprehensive inventory of the lender existing computing infrastructure, applications, data stores, and integration points, as the migration plan must account for every component of the technology environment that will be affected by the move to the cloud. The inventory process identifies the servers, databases, middleware, and applications that constitute the current environment, along with the dependencies between them, the performance characteristics of each component, and the business criticality of each application. The assessment also examines the data that flows through the environment, including borrower data, loan data, credit data, and the regulatory data that is subject to compliance requirements, as the data classification and the regulatory considerations associated with each data type will influence the cloud architecture and the cloud provider selection. The assessment phase is the foundation of the migration plan, and its thoroughness determines the accuracy of the migration timeline, the budget, and the risk assessment.
The cloud provider selection is a decision that shapes every subsequent aspect of the migration and the post-migration operation, and mortgage lenders must evaluate providers on dimensions that include the provider security posture, its compliance certifications, its service level agreements, its pricing model, and its ability to support the specific workloads that the lender intends to run in the cloud. The major cloud providers, including Amazon Web Services, Microsoft Azure, and Google Cloud Platform, offer a broad range of infrastructure and platform services that can support mortgage lending workloads, but the differences between the providers in areas such as data residency options, regulatory compliance tooling, and the availability of specialized services for data encryption and key management can be significant. Lenders in regulated industries like mortgage lending should prioritize providers that have demonstrated experience serving financial services clients and that maintain the compliance certifications, such as SOC 2 Type II and PCI DSS, that the lender own regulatory and audit requirements demand.
The migration strategy that a lender selects depends on the characteristics of the applications and data that are being migrated, and the industry has developed a set of migration approaches that are commonly described as the rehost, refactor, rearchitect, and replace strategies. The rehost approach, often called lift-and-shift, involves moving the application to the cloud with minimal changes to the application architecture, essentially replicating the on-premise environment in the cloud. The rehost approach is the fastest and the least expensive migration strategy, but it does not take full advantage of the cloud native capabilities, and the resulting environment may not achieve the cost and performance benefits that a more thorough migration would deliver. The refactor approach involves making moderate changes to the application to adapt it to the cloud environment, such as modifying the database connection logic or updating the authentication mechanism, while retaining the core application architecture. The rearchitect approach involves a more substantial redesign of the application to take advantage of cloud native services and architectures, such as microservices and containerization, and the replace approach involves retiring the legacy application and adopting a cloud native replacement, which may be a software-as-a-service solution or a purpose-built cloud application.
The data migration component of a cloud transition is one of the most complex and risk-laden aspects of the migration, as mortgage lenders maintain large volumes of sensitive borrower data, loan data, and regulatory data that must be transferred from the on-premise environment to the cloud environment without loss, corruption, or unauthorized access. The data migration plan must address the data mapping between the source and target environments, the data transformation that is required to adapt the data to the cloud data store schema, the data validation procedures that will confirm the integrity of the migrated data, and the data transfer mechanism that will move the data securely from the on-premise environment to the cloud. For large data volumes, the transfer may require dedicated network connections between the lender on-premise environment and the cloud provider, or in some cases the physical shipment of storage devices to the cloud provider for direct loading, as the time required to transfer large data volumes over standard internet connections may be prohibitive.
The security architecture for the cloud environment must be designed to meet the same regulatory and compliance requirements that governed the on-premise environment, and in many cases the cloud security architecture must exceed the on-premise security posture to satisfy the expectations of regulators and auditors who may apply heightened scrutiny to cloud-based systems. The cloud security architecture encompasses the network security controls, such as firewalls and network segmentation, that protect the cloud environment from unauthorized access, the identity and access management controls that govern who can access the cloud resources and what actions they can perform, the data encryption controls that protect data at rest and in transit, and the monitoring and logging controls that provide visibility into the cloud environment and support the audit and compliance processes. The security architecture should be designed according to the principle of least privilege, in which every user and every application is granted only the minimum access necessary to perform its function, and the architecture should incorporate multi-factor authentication, encryption key management, and continuous security monitoring as foundational controls.
The regulatory considerations for a mortgage lender cloud migration are extensive and require careful coordination between the technology team, the compliance team, and the lender legal counsel, as the migration touches on regulatory requirements that span data privacy, information security, consumer protection, and operational resilience. The Federal Financial Institutions Examination Council has published guidance on the use of cloud computing by financial institutions, and the guidance establishes expectations for the due diligence that a lender should perform before adopting cloud services, the contractual arrangements that should be in place with the cloud provider, and the ongoing oversight that the lender should maintain over the cloud environment. The Consumer Financial Protection Bureau has also issued guidance on data security that applies to the handling of consumer financial information in cloud environments, and mortgage lenders must ensure that their cloud architecture and their cloud provider arrangements are consistent with all applicable regulatory requirements.
The migration execution phase involves the actual movement of applications and data from the on-premise environment to the cloud, and the execution plan should be structured to minimize disruption to the lender ongoing business operations. The migration is typically executed in phases, with the least critical applications and the least sensitive data migrated first, followed by progressively more critical and sensitive workloads as the migration team gains confidence in the cloud environment and the migration processes. Each migration phase should include a rollback plan that allows the team to revert to the on-premise environment if the cloud migration encounters issues that cannot be resolved within an acceptable timeframe, and the rollback plan should be tested before the migration to ensure that it functions correctly. The migration execution should also include comprehensive testing of each application after it is migrated to the cloud, including functional testing, performance testing, security testing, and integration testing, to confirm that the application operates correctly in the cloud environment and that it integrates properly with the other applications and systems that it depends on.
The post-migration optimization phase is the period after the initial migration in which the lender fine-tunes the cloud environment to improve performance, reduce cost, and take advantage of cloud native capabilities that were not part of the initial migration. The optimization process includes the analysis of cloud resource utilization, which identifies computing resources that are over-provisioned or under-provisioned relative to the actual demand, and the adjustment of resource allocations to right-size the environment. The optimization also includes the adoption of cloud native services that can replace legacy components with more efficient or more capable alternatives, such as replacing a self-managed database with a managed database service that handles patching, backup, and scaling automatically. The cost optimization is a particularly important aspect of the post-migration phase, as the consumption-based pricing model of the cloud means that inefficient resource usage translates directly into unnecessary cost, and the lender should implement cost monitoring and cost management tools to identify and address cost inefficiencies on an ongoing basis.
The organizational change management associated with a cloud migration is a dimension that is often underestimated but that can determine the success or failure of the migration, as the transition to cloud infrastructure requires the lender technology team to develop new skills, adopt new processes, and operate in a fundamentally different model than the on-premise environment. The cloud operating model shifts the technology team focus from hardware management and data center operations to cloud service management, automation, and architecture, and the team must develop expertise in cloud platform services, infrastructure-as-code, and cloud security practices. The training and skill development for the technology team should begin during the assessment phase and should continue through the migration and into the post-migration period, as the team must be prepared to operate and optimize the cloud environment on an ongoing basis. The organizational change also extends to the business stakeholders, who must understand the capabilities and the limitations of the cloud environment and who must adapt their expectations and their processes to the new operating model.
The cost analysis of a cloud migration must account for both the one-time migration costs and the ongoing operational costs, and the analysis should compare the total cost of ownership of the cloud environment against the total cost of ownership of the on-premise environment over a multi-year horizon. The one-time migration costs include the assessment and planning effort, the cloud provider setup, the data migration, the application modification, the testing, and the parallel running period during which both the on-premise and cloud environments are operational. The ongoing cloud costs include the consumption-based charges for computing, storage, and network resources, the managed service charges for any cloud native services that the lender adopts, and the ongoing operational costs for the cloud management and monitoring tools and the cloud operations team. The cost analysis should also account for the costs that are eliminated by the migration, including the hardware refresh costs, the data center facility costs, and the hardware maintenance and support costs that the lender no longer incurs after the migration.
The timeline for a cloud migration varies significantly based on the size and complexity of the lender technology environment, the migration strategy that is selected, and the resources that are dedicated to the migration effort. For a small lender with a relatively simple technology environment and a rehost migration strategy, the migration can be completed in a period of three to six months. For a midsize lender with a more complex environment and a mix of migration strategies, the migration may extend over a period of six to eighteen months. For a large lender with a highly complex environment, numerous legacy applications, and extensive regulatory requirements, the migration may span two to three years or more, as the lender migrates applications in phases and addresses the integration and compliance challenges that arise at each stage. The migration timeline should be communicated to all stakeholders, including the business leadership, the technology team, the compliance team, and the external auditors, to ensure that expectations are aligned and that the migration is properly resourced.
The vendor management considerations for a cloud migration extend beyond the cloud provider selection to include the management of the migration partners, the software vendors whose applications are being migrated, and the ongoing relationship with the cloud provider after the migration is complete. The migration partner, which may be a cloud consulting firm or a system integrator, brings expertise and experience that can accelerate the migration and reduce the risk of migration failures, and the lender should select a partner with demonstrated experience in the financial services industry and in the specific cloud platform that the lender has chosen. The software vendor considerations involve verifying that the lender existing applications are compatible with the cloud environment and that the vendor support arrangements cover the cloud deployment model, as some vendors may have different licensing or support terms for cloud-based deployments. The ongoing cloud provider relationship should be governed by a formal contract that establishes the service level commitments, the security obligations, the data handling requirements, and the audit and compliance rights that the lender requires.
In conclusion, the migration from on-premise infrastructure to cloud infrastructure is a transformative undertaking for a mortgage lender, and the success of the migration depends on the thoroughness of the assessment, the appropriateness of the migration strategy, the rigor of the security and compliance planning, the quality of the execution, and the effectiveness of the post-migration optimization. The benefits of cloud infrastructure, including scalability, cost flexibility, and access to advanced computing capabilities, are substantial and are driving the mortgage industry toward cloud adoption at an accelerating pace. However, the migration is not a simple technology project but a business transformation that touches every aspect of the lender technology operations, and it requires the commitment of leadership, the alignment of stakeholders, and the investment of resources commensurate with its scope and significance. Mortgage lenders that approach the cloud migration with the appropriate planning, expertise, and discipline will be well positioned to realize the benefits of cloud infrastructure while managing the risks that the migration entails. This article is for educational purposes only and does not constitute technology advice or a recommendation to adopt any specific cloud strategy. Lenders should consult with qualified technology and compliance professionals for guidance specific to their individual situation.

Have Questions About Your Mortgage Options?
Speak with Ebonie Beaco, Senior Mortgage Loan Officer (NMLS #2389954).
Mortgage Financing & Mortgage Education
Explore Mortgage Financing Options
Visit MortgageStrategist.net for professional services and resources.
This is a promotional link to an affiliated business of the publisher, separate from the magazine's editorial content.
Editorial Disclosure: This article is published by Mortgage & Real Estate Strategist Magazine for informational and educational purposes. It does not constitute legal, tax, financial, or investment advice. Mortgage and real estate professionals should consult appropriate experts and verify current program guidelines before making decisions based on this content.
Sources & References
Sources Last Verified: November 8, 2026
Publisher & Mortgage Strategist
Ebonie Beaco is the founder and publisher of Mortgage & Real Estate Strategist Magazine. She is a licensed mortgage loan officer (NMLS #2389954) affiliated with NEXA Lending (NMLS #1660690), providing lending services in multiple states. She covers mortgage strategy, lending programs, and real estate investing.
Read More Articles by Ebonie Beaco