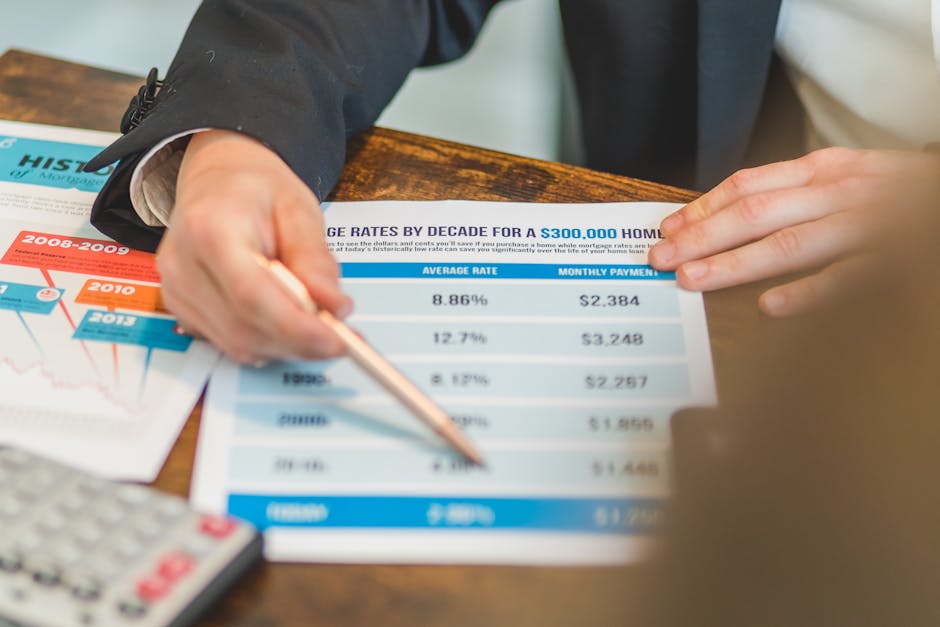
Conventional loan pricing is one of the most misunderstood aspects of the mortgage origination process, and the confusion often stems from the gap between the headline interest rate that borrowers see advertised and the actual rate that they are quoted when they apply for a loan. The difference between the advertised rate and the quoted rate is driven by the loan-level price adjustment framework, a risk-based pricing system that applies pricing adjustments to conventional loans based on the specific characteristics of the loan and the borrower. The LLPA framework is published by Fannie Mae and Freddie Mac in their respective selling guides, and it is incorporated into the pricing engines that lenders use to generate rate quotes for borrowers. Understanding the LLPA framework is essential for borrowers who want to understand why their rate differs from the advertised rate, and for mortgage professionals who must explain pricing adjustments to their clients and structure loans to minimize the cost of the adjustments.
The fundamental concept behind risk-based pricing is that the interest rate charged on a mortgage should reflect the risk of the loan to the lender and to the investor who ultimately purchases the loan. Loans with characteristics that are associated with higher default risk, such as lower credit scores, higher loan-to-value ratios, investment property occupancy, and certain property types, are assessed pricing adjustments that increase the cost of the loan. Loans with characteristics associated with lower risk, such as high credit scores, low LTV ratios, and primary residence occupancy, receive more favorable pricing or lower adjustments. The risk-based pricing approach replaces the older model of uniform pricing across all loans, and it allows the GSEs to align the pricing of each loan with its expected credit performance, creating a more efficient and equitable pricing system that charges borrowers based on the risk they present rather than subsidizing higher-risk loans with the pricing of lower-risk loans.
The credit score LLPA is one of the most significant pricing adjustments in the conventional loan framework, and it is structured as a matrix that cross-references the borrower credit score with the loan-to-value ratio. The matrix applies higher pricing adjustments to borrowers with lower credit scores and higher LTV ratios, and lower or no adjustments to borrowers with higher credit scores and lower LTV ratios. For example, a borrower with a credit score of 620 to 639 and an LTV above 95 percent might face a pricing adjustment of 3.00 to 3.50 percentage points, while a borrower with a credit score of 780 or above and the same LTV might face an adjustment of 0.00 to 0.25 percentage points. The credit score LLPA is not a fee that is paid upfront; it is a pricing adjustment that is expressed in basis points and is typically incorporated into the interest rate through a lender credit or discount point mechanism, meaning that the borrower either pays a higher rate or pays discount points to maintain the base rate.
The mechanics of how LLPAs are applied to the borrower rate quote are important to understand. The lender starts with a base rate, which is the par rate at which the lender is willing to originate the loan without any pricing adjustments or discount points. The LLPA adjustments are then added to or subtracted from the base rate, with the total adjustment expressed in basis points, where one basis point equals 0.01 percentage points. If the total LLPA is positive, meaning that the adjustments add cost to the loan, the borrower has two options: they can accept a higher interest rate that incorporates the cost of the adjustments, or they can pay discount points at closing to cover the cost and maintain the base rate. The conversion between basis points and discount points is approximately 25 basis points equals 0.25 discount points, or 0.25 percent of the loan amount. For a borrower with a $400,000 loan and a total LLPA of 100 basis points, the cost is approximately $4,000, which can be paid as a higher rate or as discount points at closing.
The loan-to-value ratio LLPA interacts with the credit score LLPA in the pricing matrix, and the combination of the two adjustments can produce significantly different pricing outcomes for borrowers with different profiles. The LTV LLPA generally applies higher adjustments to loans with higher LTV ratios, reflecting the greater risk associated with loans that have less borrower equity. A borrower with a 95 percent LTV will typically face a higher LTV-based adjustment than a borrower with a 75 percent LTV, independent of the credit score adjustment. The combined effect of the credit score and LTV adjustments is captured in the cross-referenced matrix, which ensures that the pricing reflects the interaction of both factors rather than treating them independently. Borrowers who are near a threshold in either the credit score or the LTV dimension can sometimes achieve a meaningful pricing improvement by making a small adjustment, such as increasing their down payment to move to a lower LTV bracket or improving their credit score to move to a higher credit score bracket.
The occupancy status LLPA applies different pricing adjustments based on whether the property is a primary residence, a second home, or an investment property. Primary residence loans receive the most favorable pricing, with no occupancy adjustment or a minimal adjustment, reflecting the lower default risk associated with owner-occupied properties. Second homes typically face a modest pricing adjustment, while investment properties face the most significant occupancy adjustment, often 1.00 to 3.00 percentage points depending on the LTV and other factors. The investment property adjustment reflects the higher default risk that has been historically observed on investment property loans, as borrowers in financial distress are more likely to default on an investment property than on their primary residence. The occupancy LLPA is a critical consideration for real estate investors, as the pricing adjustment can significantly affect the cost of financing and the cash flow analysis of an investment property acquisition.
The property type LLPA applies adjustments based on the type of property being financed. Single-family detached homes and standard condominiums typically receive the most favorable property type pricing, while manufactured homes, cooperative units, and certain multi-unit properties may face additional adjustments. The property type adjustments reflect the varying liquidity and performance characteristics of different property types in the event of default, as some property types are more difficult to sell or have more volatile market values than others. Borrowers financing non-standard property types should be aware that the property type LLPA may affect their pricing, and should work with their loan officer to understand the applicable adjustments and to explore whether any program variations or lender options can mitigate the adjustment. The property type LLPA is generally smaller than the credit score and occupancy adjustments, but it can still be a meaningful factor for borrowers financing property types that carry higher adjustments.
The number of units in the property triggers a multi-unit LLPA for properties with two to four units, reflecting the higher risk and complexity associated with multi-unit residential properties. The multi-unit adjustment is applied in addition to the base credit score and LTV adjustments, and it increases with the number of units, with four-unit properties typically carrying the highest adjustment. The multi-unit LLPA is relevant for owner-occupant borrowers who purchase multi-unit properties as a house-hacking strategy, as the pricing adjustment affects the cost of financing and must be factored into the cash flow analysis that includes rental income from the additional units. Despite the adjustment, multi-unit owner-occupied properties can still be financially advantageous due to the rental income offset, and the GSEs allow a portion of the rental income to be included in the borrower qualifying income, which can improve the DTI calculation and offset the impact of the pricing adjustment.
The subordinate financing LLPA applies when there is a second lien on the property at the time of conventional loan origination, such as a piggyback second mortgage or a home equity line of credit. The presence of subordinate financing increases the combined loan-to-value ratio and affects the risk profile of the first mortgage, triggering a pricing adjustment that reflects the additional risk. The subordinate financing adjustment varies based on the combined LTV and the characteristics of the second lien, and it is applied in addition to the other applicable LLPAs. Borrowers who are considering a piggyback loan structure to avoid private mortgage insurance should compare the total cost of the piggyback structure, including the subordinate financing LLPA and the second lien payments, against the cost of a single first mortgage with PMI, to determine which structure is more cost-effective for their situation.
The homeownership counseling and HomeReady and Home Possible LLPA features are important program-specific pricing considerations that can benefit certain borrowers. Fannie Mae HomeReady and Freddie Mac Home Possible are affordable lending programs that serve low-to-moderate income borrowers and properties in designated underserved areas. These programs offer reduced or eliminated LLPAs for eligible borrowers, making conventional financing more affordable for borrowers who meet the program income and eligibility requirements. The HomeReady and Home Possible programs can provide significant pricing advantages for eligible borrowers, potentially saving 1.00 to 3.00 percentage points in LLPA adjustments compared to standard conventional pricing. Borrowers who believe they may be eligible for these programs should ask their loan officer about the eligibility requirements and the pricing benefits, as the programs are not always proactively offered and may require the borrower to request consideration.
The first-time homebuyer LLPA is a program-specific adjustment that applies to certain first-time homebuyer loan programs, and it can be either a positive or negative adjustment depending on the program structure. Some first-time homebuyer programs offer reduced LLPAs to make conventional financing more accessible to borrowers entering the housing market for the first time, while others may apply a modest adjustment to reflect the higher risk associated with borrowers who have no prior mortgage payment history. The first-time homebuyer adjustment interacts with the standard credit score and LTV adjustments, and the net effect depends on the specific program and the borrower profile. Borrowers who are first-time homebuyers should explore the available program options and should understand how the first-time homebuyer LLPA affects their pricing compared to standard conventional loan pricing.
The timing and market dynamics of LLPA changes are important for mortgage professionals to track, as the GSEs periodically update the LLPA matrices to reflect evolving risk assessment and market conditions. LLPA changes are announced through selling guide updates and lender letters, and they become effective on a specified date, requiring lenders to update their pricing engines and rate sheets accordingly. The changes can affect the competitiveness of conventional loan pricing relative to other loan programs, and they can shift the borrower profile that is best served by conventional versus alternative financing options. Recent LLPA updates have included adjustments to the credit score matrix that reduced the pricing adjustments for certain borrower segments and increased them for others, reflecting a policy emphasis on equity and affordability in conventional loan pricing. Mortgage professionals who stay current with LLPA changes can provide more accurate pricing guidance to borrowers and can identify program changes that may benefit specific borrower profiles.
The interaction between LLPAs and the interest rate lock strategy is a consideration that borrowers and loan officers should address during the origination process. The LLPAs that apply to a loan are determined at the time of the rate lock, based on the loan characteristics and borrower profile at that point. If the borrower credit score, LTV, or other relevant characteristic changes between the initial application and the rate lock, the applicable LLPAs may change, affecting the final rate. Borrowers should be aware that actions taken during the application process, such as increasing the down payment to improve the LTV or addressing credit report issues to improve the score, can affect the LLPAs and the final pricing. Loan officers should monitor the loan characteristics throughout the process and should advise borrowers on actions that can improve the pricing outcome before the rate lock is executed.
The impact of LLPAs on the annual percentage rate versus the note rate is a distinction that borrowers should understand when comparing loan offers. The note rate is the interest rate that is applied to the loan principal to calculate the monthly principal and interest payment, and it is the rate that borrowers typically focus on when comparing loans. The annual percentage rate, by contrast, is a broader measure of the cost of borrowing that includes the note rate plus certain closing costs, discount points, and lender fees expressed as an annualized rate. The LLPAs that are paid as discount points at closing are included in the APR calculation, while the LLPAs that are incorporated into a higher note rate are reflected in the note rate itself but may not be separately itemized in the APR. Borrowers comparing loan offers should look at both the note rate and the APR to understand the total cost of each option, and should ask the lender for a clear explanation of how the LLPAs are being applied in each quote. A loan with a lower note rate but higher discount points may have a higher APR than a loan with a higher note rate but no discount points, and the borrower should evaluate which structure is more advantageous based on their expected holding period and their preference for upfront versus ongoing costs. Understanding the relationship between LLPAs, the note rate, and the APR is an essential element of mortgage literacy that empowers borrowers to make informed decisions and to compare loan offers accurately across lenders and loan structures.
The strategic implications of the LLPA framework for borrowers center on the ability to optimize the loan structure and borrower profile to minimize the total pricing adjustment. Borrowers who are near a threshold in the credit score or LTV matrix can achieve meaningful pricing improvements by crossing the threshold, and the cost of the action required to cross the threshold should be compared against the pricing benefit. For example, a borrower who is near the boundary between the 680-699 and 700-759 credit score brackets may benefit from paying down a credit card balance to improve their score by a few points, if the LLPA reduction exceeds the cost of the balance paydown. Similarly, a borrower near the 95 percent LTV boundary may benefit from increasing their down payment by a small amount to move to the 90.01-95.00 percent bracket, if the LLPA reduction exceeds the additional down payment cost on a per-payment basis. Understanding the LLPA matrix and the threshold effects is a powerful tool for borrowers and loan officers who want to structure the loan for the most favorable pricing outcome, and it is one of the most concrete ways that a knowledgeable mortgage professional adds value to the origination process. This article is for educational purposes only and does not constitute a loan offer or financial advice. Borrowers should consult a licensed mortgage professional for current LLPA schedules and pricing specific to their situation, as the LLPA framework is subject to periodic updates by the GSEs.

Have Questions About Your Mortgage Options?
Speak with Ebonie Beaco, Senior Mortgage Loan Officer (NMLS #2389954).
Mortgage Financing & Mortgage Education
Explore Mortgage Financing Options
Visit MortgageStrategist.net for professional services and resources.
This is a promotional link to an affiliated business of the publisher, separate from the magazine's editorial content.
Editorial Disclosure: This article is published by Mortgage & Real Estate Strategist Magazine for informational and educational purposes. It does not constitute legal, tax, financial, or investment advice. Mortgage and real estate professionals should consult appropriate experts and verify current program guidelines before making decisions based on this content.
Sources & References
- Fannie Mae, Selling Guide: Loan-Level Price Adjustment Matrix and Risk-Based Pricing Documentation, 2026
- Freddie Mac, Single-Family Seller/Servicer Guide: Loan-Level Price Adjustments and Pricing Framework, 2026
- Fannie Mae, HomeReady Program Eligibility and Pricing Adjustment Guidance, 2026
- Freddie Mac, Home Possible Program Eligibility and Pricing Documentation, 2026
- Consumer Financial Protection Bureau, Mortgage Rate Pricing and Risk-Based Adjustment Guidance for Borrowers, 2026
Sources Last Verified: November 8, 2026
Publisher & Mortgage Strategist
Ebonie Beaco is the founder and publisher of Mortgage & Real Estate Strategist Magazine. She is a licensed mortgage loan officer (NMLS #2389954) affiliated with NEXA Lending (NMLS #1660690), providing lending services in multiple states. She covers mortgage strategy, lending programs, and real estate investing.
Read More Articles by Ebonie Beaco