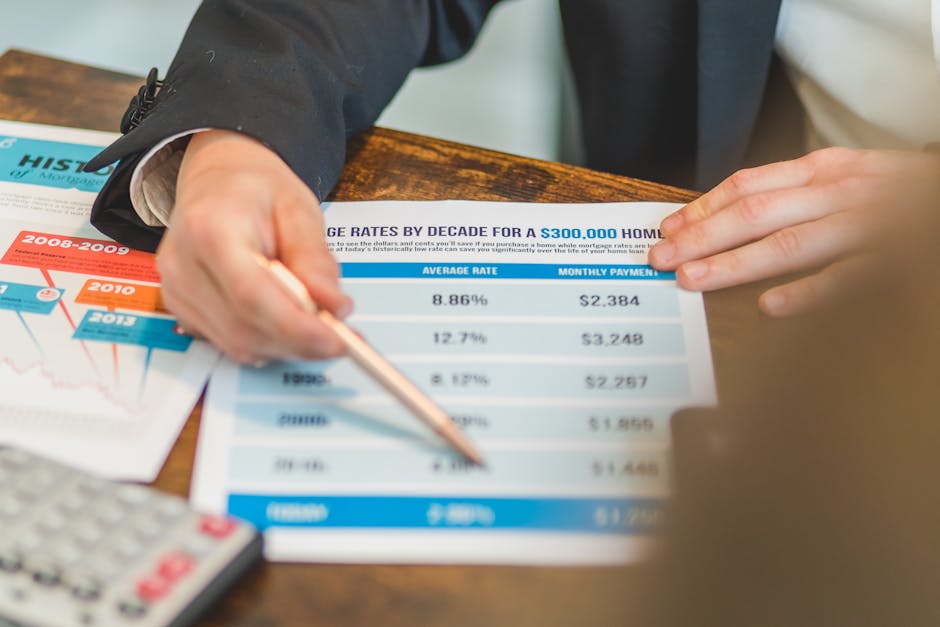
The pricing of self-employed mortgage loans is a subject that generates significant interest and not a small amount of confusion among self-employed borrowers, many of whom assume that self-employment automatically results in higher mortgage rates or less favorable loan terms. The reality is more nuanced, as the pricing of a self-employed mortgage depends on a combination of factors including the loan program, the borrower credit profile, the loan-to-value ratio, the income documentation method, and the competitive dynamics of the lender offering the loan. Understanding how lenders price self-employed borrower risk is essential for self-employed borrowers who want to secure the most favorable mortgage terms available in the current market.
The conforming loan pricing for self-employed borrowers is identical to the conforming loan pricing for W-2 borrowers, provided that the self-employed borrower qualifies under the standard Fannie Mae or Freddie Mac guidelines. This is a point that is often misunderstood by self-employed borrowers, who may assume that their self-employment status automatically subjects them to higher rates or less favorable terms. In the conforming loan market, the pricing is driven by the loan-level pricing adjustments that Fannie Mae and Freddie Mac apply based on the loan-to-value ratio, the credit score, the occupancy type, and the property type, not by the employment status of the borrower. A self-employed borrower with a 760 credit score and a 20 percent down payment will receive the same conforming rate as a W-2 borrower with the same profile.
The Non-QM loan pricing for self-employed borrowers is where the self-employment status has a direct impact on the rate, as Non-QM loans are not priced off the GSE pricing matrices and are instead priced by each lender based on their own risk assessment and return requirements. Non-QM bank statement loans, which use bank deposit income rather than tax return income, typically carry rates that are 75 to 200 basis points higher than conforming rates, reflecting the higher risk that the lender assumes by relying on alternative income documentation and by holding the loan in portfolio or selling it into the private-label securitization market. The rate premium on Non-QM loans varies by lender, by program, and by the borrower profile, and the competitive landscape among Non-QM lenders has compressed the premium in recent years.
The risk factors that lenders consider when pricing self-employed mortgage loans include the stability and trend of the business income, the length of the self-employment history, the industry and business type, the complexity of the business structure, and the adequacy of the documentation. Lenders view a borrower with a five-year self-employment history and steadily increasing income as lower risk than a borrower who has been self-employed for only two years with variable or declining income. Lenders also consider the industry in which the business operates, as some industries are more volatile or more susceptible to economic downturns than others. A borrower in a stable professional services business may receive more favorable pricing than a borrower in a cyclical or seasonal business, all else being equal.
The loan-to-value ratio is a pricing factor that affects self-employed borrowers in the same way it affects all borrowers, with lower LTV ratios generally resulting in more favorable pricing. For conforming loans, the loan-level pricing adjustment for LTV is applied uniformly regardless of employment status, and a borrower with a 20 percent down payment will receive better pricing than a borrower with a 5 percent down payment. For Non-QM loans, the LTV pricing impact may be more pronounced, as Non-QM lenders often apply larger rate adjustments for higher LTV ratios to compensate for the additional risk of combining alternative income documentation with a higher loan balance. Self-employed borrowers who can make a larger down payment will generally receive more favorable pricing on both conforming and Non-QM loans.
The credit score impact on self-employed mortgage pricing is significant, as it is for all borrowers, but it may be weighted more heavily by Non-QM lenders who are already accepting the additional risk of alternative income documentation. A credit score of 740 or higher will generally result in the best available pricing on both conforming and Non-QM loans, while scores below 680 may result in rate increases or may limit the available loan programs. Self-employed borrowers should review their credit reports and address any derogatory items or errors before applying for a mortgage, as the credit score is one of the factors that the borrower can most directly control, and an improvement of even 20 to 40 points can result in meaningfully better pricing over the life of the loan.
The competitive landscape among lenders that serve the self-employed segment has evolved significantly, with an increasing number of Non-QM lenders entering the market and competing for self-employed borrower business. The competition among Non-QM lenders has compressed the rate premium that Non-QM loans carry relative to conforming loans, and has expanded the range of program options available to self-employed borrowers. The competitive landscape also varies by geography, as some lenders focus on specific regions or markets, and self-employed borrowers should shop among multiple lenders to ensure that they are receiving the most competitive pricing available. The rate difference between the most competitive and the least competitive Non-QM lender for the same borrower profile can be 50 basis points or more, which translates to a significant difference in the total interest paid over the life of the loan.
The rate lock strategy for self-employed borrowers involves the same considerations as for W-2 borrowers, with the added complexity that the self-employed loan may take longer to process, which can affect the rate lock period and the lock cost. Self-employed borrowers should discuss the rate lock strategy with their loan officer early in the process, as the longer processing timeline for self-employed loans may require a longer rate lock period, which can increase the lock cost or the rate. Some lenders offer extended rate lock periods for self-employed loans, while others may charge a fee for the longer lock or may require the borrower to accept a slightly higher rate for the extended lock. The rate lock decision should be made in consultation with the loan officer, based on the borrower timeline and the market rate expectations.
The discount points consideration for self-employed borrowers is the same as for W-2 borrowers, with the borrower having the option to pay discount points to reduce the interest rate. The decision to pay discount points should be based on a break-even analysis that compares the upfront cost of the points against the monthly savings from the lower rate, and the break-even period should be shorter than the borrower expected holding period for the loan. For self-employed borrowers who are using a Non-QM loan, the discount point pricing may be different from the conforming loan discount point pricing, and the borrower should ask the lender for a clear explanation of the point pricing and the rate reduction that each point provides.
The impact of income documentation method on pricing is most pronounced in the Non-QM market, where different income documentation programs carry different rate levels. Bank statement loans, which use 12 to 24 months of business bank deposits, typically carry the lowest rate premium among the Non-QM self-employed programs, as the bank statements provide a verifiable and objective measure of the business cash flow. Profit and loss only loans, which rely on a CPA-prepared profit and loss statement without bank statement corroboration, may carry a higher rate premium due to the lower level of documentation. Asset-based qualification programs, which use the borrower liquid assets rather than income to qualify, carry the highest rate premium, as the lender is relying on asset depletion rather than ongoing income to support the loan repayment.
The pricing difference between 12-month and 24-month bank statement programs is a consideration for self-employed borrowers who are evaluating Non-QM loan options. Programs that use 24 months of bank statements typically offer slightly lower rates than programs that use only 12 months, as the longer history provides the lender with a more reliable basis for the income calculation and reduces the risk of income variability. However, the 24-month requirement may disadvantage borrowers whose business has been growing rapidly, as the older 12 months may show lower income than the more recent 12 months. Borrowers should compare the rate difference between the 12-month and 24-month programs and should consider which program provides the better combination of qualifying income and rate pricing for their specific situation.
The property type impact on self-employed mortgage pricing follows the same general principles as for all mortgages, with single-family primary residences receiving the most favorable pricing and investment properties and multi-unit properties carrying rate adjustments. For Non-QM loans, the property type adjustments may be more significant, as some Non-QM lenders restrict their programs to single-family primary residences and may not offer financing for investment properties or multi-unit properties. Self-employed borrowers who are purchasing or refinancing a property that is not a standard single-family primary residence should verify the property type eligibility with their lender and should be prepared for possible rate adjustments or program restrictions based on the property type.
The seasonal income consideration is a pricing factor for self-employed borrowers whose business income fluctuates seasonally, as lenders may view seasonal income variability as a risk factor that affects the loan pricing. A borrower whose business generates 70 percent of its annual revenue in the second and third quarters may face questions about the income stability during the first and fourth quarters, and the lender may adjust the income calculation or the pricing to account for the seasonal variability. Borrowers with seasonal income should provide the lender with a clear explanation of the business seasonality and should demonstrate that the business has a consistent multi-year track record of generating sufficient annual income to support the mortgage payment, regardless of the intra-year timing of the revenue.
The amortization period effect on self-employed mortgage pricing is a consideration for borrowers who are evaluating different loan terms, as the amortization period affects both the monthly payment and the interest rate. The 30-year amortization provides the lowest monthly payment but typically carries the highest interest rate, while the 15-year amortization provides a lower rate but a higher monthly payment. Some Non-QM lenders offer 40-year amortization periods, which reduce the monthly payment further but increase the total interest paid over the life of the loan and may carry a rate premium. Self-employed borrowers should evaluate the amortization options in the context of their cash flow situation and their long-term financial goals, and should select the amortization period that provides the best balance of payment affordability and total cost efficiency.
In conclusion, the pricing of self-employed mortgage loans is a multifaceted subject that reflects the risk factors, the loan program selection, the competitive dynamics, and the borrower-specific characteristics that lenders evaluate when underwriting and pricing loans for self-employed borrowers. Self-employed borrowers who understand the pricing factors and who work to optimize their credit profile, their down payment, their documentation, and their lender selection can secure mortgage terms that are competitive with or close to the terms available to W-2 borrowers. The key is to approach the mortgage process with preparation and knowledge, to shop among multiple lenders, and to work with a mortgage professional who understands the self-employed segment and who can guide the borrower to the most favorable pricing available. This article is for educational purposes only and does not constitute a loan offer or financial advice. Borrowers should consult a licensed mortgage professional for pricing and program information specific to their individual situation.

Have Questions About Your Mortgage Options?
Speak with Ebonie Beaco, Senior Mortgage Loan Officer (NMLS #2389954).
Mortgage Financing & Mortgage Education
Explore Mortgage Financing Options
Visit MortgageStrategist.net for professional services and resources.
This is a promotional link to an affiliated business of the publisher, separate from the magazine's editorial content.
Editorial Disclosure: This article is published by Mortgage & Real Estate Strategist Magazine for informational and educational purposes. It does not constitute legal, tax, financial, or investment advice. Mortgage and real estate professionals should consult appropriate experts and verify current program guidelines before making decisions based on this content.
Sources & References
- Fannie Mae Self-Employed Income Analysis
- Freddie Mac Seller Guide
- CFPB Ability-to-Repay Rule
- IRS Schedule C Instructions
- NMLS Consumer Access
Sources Last Verified: November 8, 2026
Publisher & Mortgage Strategist
Ebonie Beaco is the founder and publisher of Mortgage & Real Estate Strategist Magazine. She is a licensed mortgage loan officer (NMLS #2389954) affiliated with NEXA Lending (NMLS #1660690), providing lending services in multiple states. She covers mortgage strategy, lending programs, and real estate investing.
Read More Articles by Ebonie Beaco